
tax
Graduated Income Tax or 8% Special Tax: Which is Better?
Posted by Accountable PH
onOctober 16, 2025
Freelancers, professionals, and sole proprietors in the Philippines may choose between the graduated income tax rates and the 8% income tax rate, provided they meet the eligibility requirements.
Which one is better?
The 8% income tax rate may be more beneficial for taxpayers with relatively low business expenses because it is based on gross sales or gross receipts and replaces the percentage tax under Section 116 of the Tax Code. On the other hand, the graduated income tax option may result in a lower overall tax liability when a business has substantial allowable expenses that reduce its taxable income.
The better option depends on several factors, including your gross sales or gross receipts, allowable expenses, VAT registration, other sources of income, and whether you also earn compensation income.
Quick comparison: Graduated income tax vs. 8% income tax
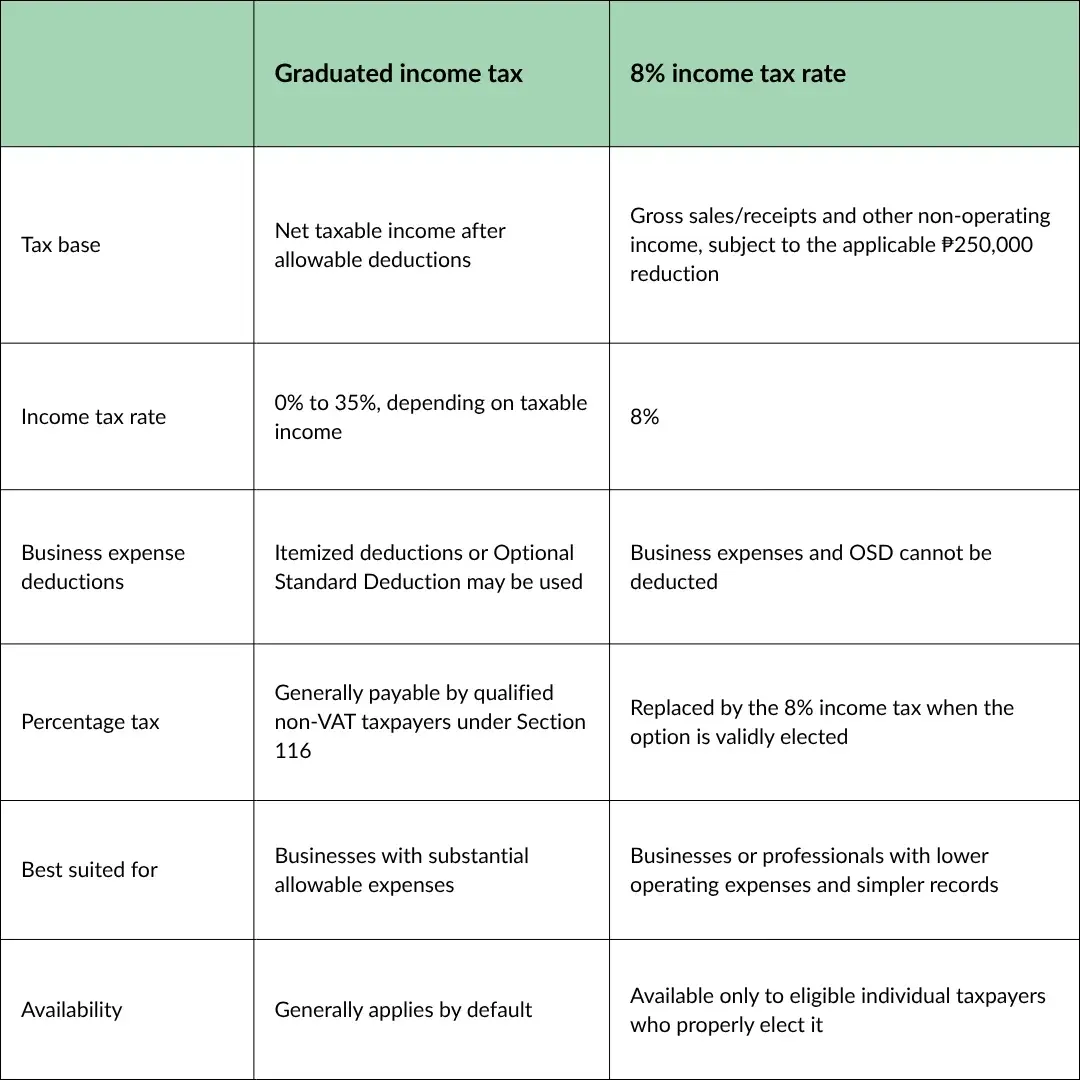
The 8% option is not simply an 8% version of the graduated tax. It uses a different tax base and replaces both the graduated income tax on business income and the percentage tax under Section 116.
What is the graduated income tax rate?
The most common and widely used income tax rate for individual taxpayers is the graduated income tax. It follows a set of tax rates which increases as the taxable amount rises, this is also known as progressive income tax.
Under the graduated income tax system, your tax is based on your taxable income—not automatically on your total gross sales.
For a self-employed individual or professional, taxable business income is generally computed by subtracting allowable deductions from gross income. The taxpayer may choose between:
Itemized deductions, which are based on qualified and properly substantiated business expenses; or
Optional Standard Deduction, or OSD, which allows an individual taxpayer to deduct up to 40% of gross sales instead of claiming individual expenses.
The deduction method selected for the taxable year generally cannot be changed midway through that year.
Graduated income tax rates effective January 1, 2023 onward
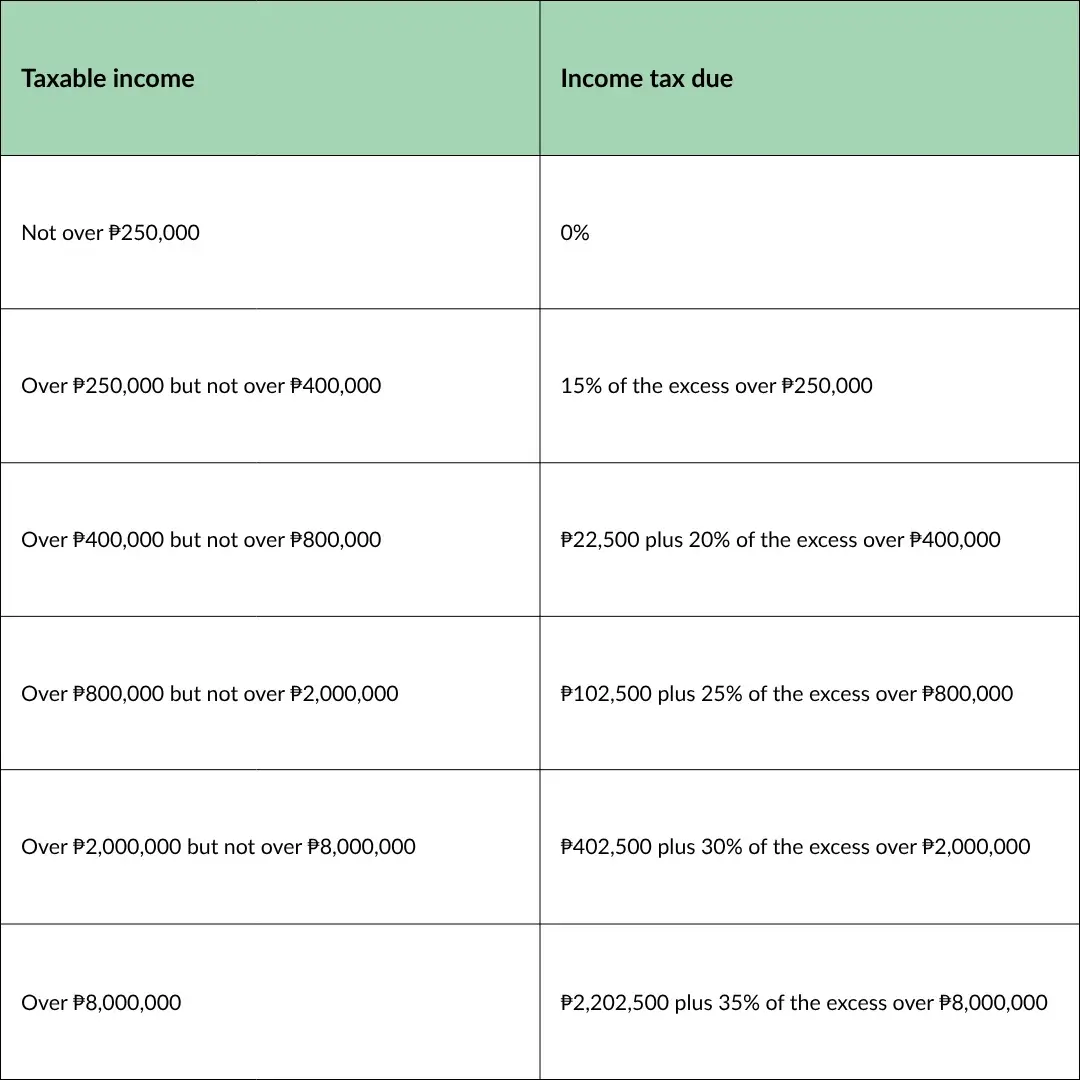
Source: BIR Form No. 1701-MS Guidelines and Instructions
These brackets apply to taxable income after the applicable deductions, not directly to gross sales.
Does graduated income tax include percentage tax?
For a non-VAT taxpayer whose transactions fall under Section 116, choosing the graduated income tax rates generally means paying a separate 3% percentage tax on quarterly gross sales.
This percentage tax is separate from the income tax calculated using the graduated tax table. Qualified taxpayers who properly elect the 8% income tax option are no longer required to pay this Section 116 percentage tax for the year covered by the election.
What is the 8% income tax rate?
The TRAIN Law introduced the optional 8% income tax rate for eligible self-employed individuals and professionals. Although it is sometimes called the “8% special tax,” the official term used by the BIR is the 8% income tax rate option.
For a purely self-employed individual or professional, the tax is generally computed as:
8% × (gross sales + other non-operating income − ₱250,000)
The computation and eligibility rules for this option are provided under BIR Revenue Regulations No. 8-2018.
The 8% tax replaces:
The graduated income tax on the taxpayer’s business or professional income; and
The percentage tax imposed under Section 116.
Unlike the graduated option, the taxpayer cannot deduct actual business expenses or claim OSD when computing the 8% income tax.
A note on “gross sales” and “gross receipts”
Older BIR regulations and forms frequently use the phrase “gross sales or receipts.” Under the Ease of Paying Taxes Act and its implementing rules, including Revenue Regulations No. 3-2024, the BIR now uses gross sales for both goods and services. Invoices, rather than official receipts, are now the primary documents evidencing sales of goods and services.
For service providers, gross sales generally cover the contract price, professional fee, service fee, rental, or similar amount for services already rendered, excluding amounts specifically excluded by law.
Who can avail the 8% income tax rate?
The option may generally be available to the following individual taxpayers:
Sole proprietors
Freelancers
Independent contractors
Consultants
Licensed and non-licensed professionals
Online sellers registered as individual taxpayers
Mixed-income earners who receive both compensation income and income from a business or profession
To qualify, the taxpayer's gross sales or gross receipts, together with other non-operating income, must not exceed the applicable VAT threshold. As of the date of this article, the threshold is ₱3 million.
The taxpayer must also be qualified as a non-VAT individual taxpayer and must not be subject to another percentage tax under Title V of the Tax Code, except the percentage tax under Section 116.
The Ease of Paying Taxes Act provides for periodic adjustment of the VAT threshold using the Consumer Price Index. Taxpayers should therefore confirm the applicable threshold for the particular taxable year being filed.
Who cannot avail the 8% income tax rate?
The 8% option is not available to:
Individuals earning purely compensation income
VAT-registered taxpayers
Taxpayers whose gross sales and other non-operating income exceed the applicable VAT threshold
Individuals subject to other percentage taxes under Title V, except those subject to Section 116
Partners of a General Professional Partnership with respect to their distributive share from the partnership
Individuals enjoying an income tax exemption, such as qualified BMBEs claiming the applicable income tax exemption
Corporations, ordinary partnerships, cooperatives, and other non-individual taxpayers
Corporations and partnerships follow their applicable corporate or partnership tax rules and cannot use the individual 8% income tax option.
How does the ₱250,000 reduction work?
The ₱250,000 reduction depends on whether the taxpayer is purely self-employed or a mixed-income earner.
Purely self-employed individuals and professionals
A taxpayer who earns purely from a business or profession may subtract up to ₱250,000 from gross sales and other non-operating income before applying the 8% rate.
Example:
Gross sales: ₱600,000
Less allowable reduction: ₱250,000
Tax base: ₱350,000
8% income tax: ₱28,000
Mixed-income earners
A mixed-income earner receives both compensation income and income from self-employment or a profession.
The ₱250,000 reduction does not apply to the mixed-income earner’s business or professional income under the 8% option. This is because the ₱250,000 zero-tax bracket is already incorporated into the graduated tax rates applied to compensation income.
Example:
Business gross sales: ₱600,000
Allowable ₱250,000 reduction: None
8% tax on business income: ₱48,000
Compensation income: Taxed separately using the graduated rates
Any unused portion of the ₱250,000 bracket from compensation income cannot be transferred or deducted from the business income subject to the 8% rate.
How do you choose the 8% income tax rate?
Being eligible does not automatically place a taxpayer under the 8% option. The taxpayer must signify the election properly.
For a newly registered business or professional
The intention to use the 8% rate may be indicated:
During registration using BIR Form 1901; or
Through the initial quarterly return—BIR Form 2551Q or BIR Form 1701Q—after the business or professional practice begins.
For an existing taxpayer in succeeding years
The taxpayer may elect the 8% option:
By filing BIR Form 1905 at the beginning of the taxable year to update the registration; or
Upon filing the first quarterly percentage tax return or first quarterly income tax return for the year.
The taxpayer must elect the 8% option every taxable year. Once validly elected, the choice is generally irrevocable for that year. A taxpayer who fails to make the election properly will remain subject to the graduated income tax rates and the applicable percentage tax.
See BIR Revenue Memorandum Order No. 23-2018 for the election and filing procedures.
Do taxpayers under the 8% option still have filing and recordkeeping obligations?
Yes. Choosing the 8% option does not remove the taxpayer’s other compliance responsibilities.
A qualified taxpayer under the 8% option generally must still:
File quarterly income tax returns
Maintain registered books of accounts
Issue duly registered invoices
Keep supporting records
Declare the 8% election for each taxable year
A taxpayer who validly elected the 8% option is generally not required to file the quarterly percentage tax return for the year covered by the election.
What happens if you exceed the VAT threshold?
A taxpayer who initially chose the 8% option but later exceeds the applicable VAT threshold during the taxable year will no longer qualify for the 8% rate.
The taxpayer will generally:
Become subject to graduated income tax rates for the taxable year
Receive a tax credit for income tax payments previously made under the 8% option
Become liable for VAT prospectively
Update the BIR registration to reflect the change from non-VAT to VAT
Pay the applicable percentage tax for the period from the beginning of the year until VAT liability begins
Under existing BIR guidance, VAT liability begins prospectively from the first day of the month following the month in which the threshold was exceeded. The registration update should be completed within the month following the month of the threshold breach.
Which is better: Graduated income tax or 8% income tax?
Neither option is automatically better for everyone. The correct comparison should include both income tax and, when applicable, the 3% percentage tax.
The 8% income tax may be better when:
Your business has relatively low operating expenses
You do not have enough allowable and substantiated expenses to reduce taxable income significantly
You prefer a simpler tax computation
Your gross sales remain within the VAT threshold
The combined graduated income tax and percentage tax would be higher than the 8% tax
The graduated income tax may be better when:
You have substantial ordinary and necessary business expenses
You can properly substantiate your itemized deductions
Your net taxable income is considerably lower than your gross sales
Your computed graduated income tax plus percentage tax is lower than the 8% tax
You do not qualify for the 8% option
Below are two simplified examples showing when one tax option may result in a lower estimated tax than the other.
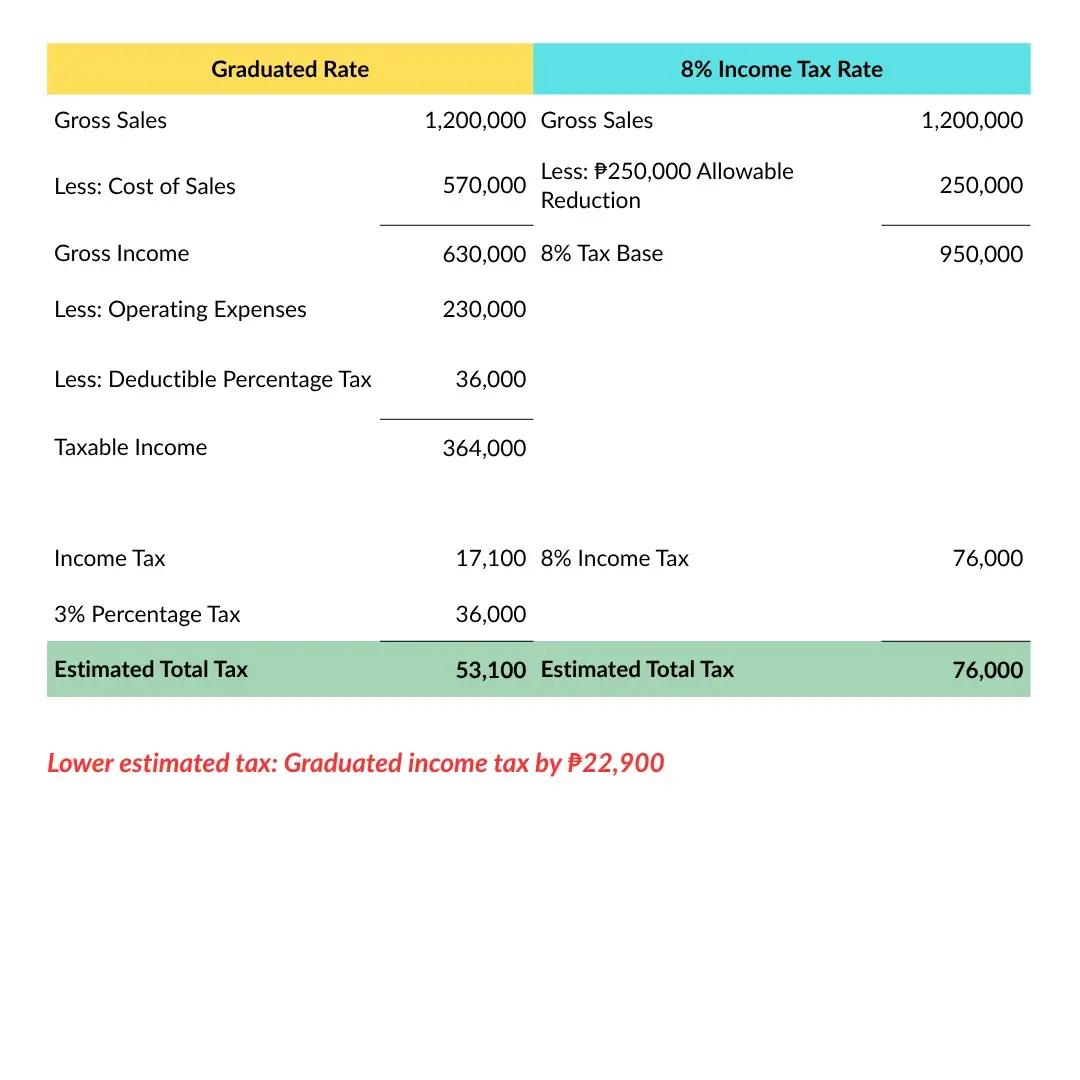
Scenario 1: With ₱1.2 million in gross sales and substantial expenses, the estimated graduated income tax and percentage tax total ₱53,100, compared with ₱76,000 under the 8% option.
Scenario 2: With ₱1.5 million in gross sales and lower deductions, the estimated graduated income tax and percentage tax total ₱112,500, compared with ₱100,000 under the 8% option.
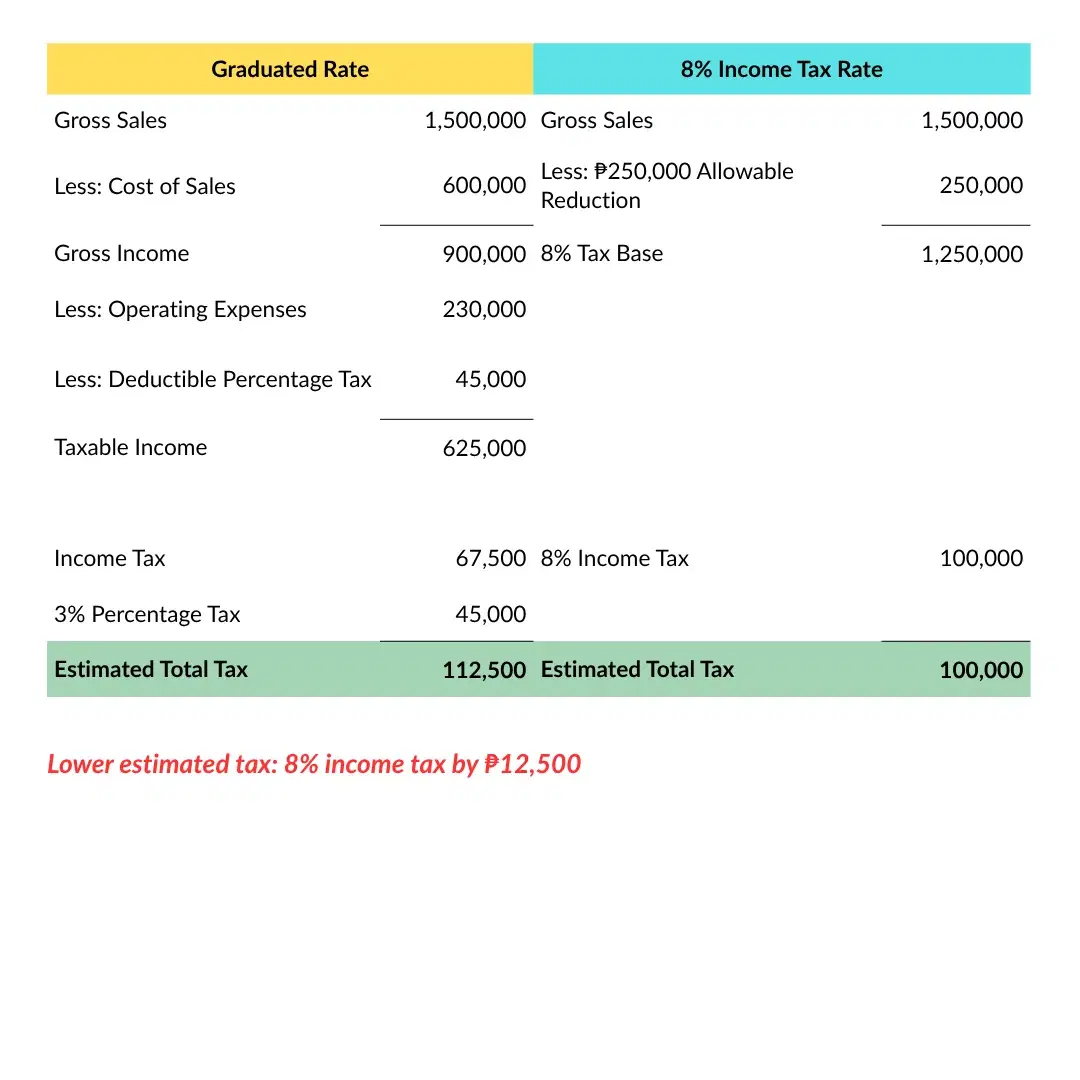
These simplified computations assume a purely self-employed, non-VAT individual taxpayer using itemized deductions under the graduated income tax option.
The taxpayer has no compensation income, other non-operating income, or withholding tax credits. All listed expenses are assumed to be allowable, business-related, and properly supported.
For illustration purposes, the 3% percentage tax is not included in the stated operating expenses and is treated as a deductible business tax, subject to the applicable tax rules and the taxpayer’s accounting method. Actual tax due may vary.
Do not choose based only on the percentage
It may be tempting to compare 8% against the graduated rates of 15% to 35% and immediately conclude that 8% is lower. However, the two options use different tax bases.
The 8% rate is applied to gross sales after the applicable ₱250,000 reduction. The graduated rates are applied to taxable income after deductions. That means a taxpayer with high allowable expenses can have a much smaller taxable base under the graduated option.
A proper comparison should consider:
Expected annual gross sales
Allowable and supportable expenses
OSD versus itemized deductions
The 3% percentage tax
Compensation income, if any
Creditable withholding taxes
Other non-operating income
VAT registration and the applicable threshold
Need help choosing the right tax option?
Choosing the wrong option can lead to a higher tax bill, unnecessary filings, or registration issues. Before making an election, prepare a side-by-side computation using realistic sales and expense figures.
Accountable.ph provides bookkeeping and tax compliance support for freelancers, professionals, and business owners in Cebu and Manila. For Manila clients, tax-related support is provided alongside a bookkeeping package.
Our team can help you:
Organize and review your accounting records
Estimate your tax under the graduated and 8% options
Check whether you meet the eligibility requirements
Monitor your gross sales against the VAT threshold
Prepare and file the applicable tax returns
Frequently Asked Questions
Who can avail of the 8% income tax rate?
Self-employed individuals and professionals whose annual gross sales or receipts do not exceed the VAT threshold.
Can freelancers choose the 8% tax rate?
Yes, provided they meet the eligibility requirements set by the BIR.
What happens if I exceed the VAT threshold?
You may become subject to graduated income tax rates and VAT requirements.
Which is better: Graduated Tax or 8% Tax?
The answer depends on your income, expenses, and business circumstances.
Can I change my tax regime during the year?
No. The income tax regime you elect in your first quarterly income tax return generally applies for the entire taxable year. Once the election is validly made, taxpayers generally cannot switch between the graduated income tax rates and the 8% income tax rate during the same taxable year.
Tags:
8% Income Tax, Accounting, Cebu, Freelancer Tax, Graduated, Graduated Income Tax, Income, Outsourcing, Self-Employed Tax, Service provider, Services, Struggles, Tax
2024
2025
2026
September
August
July